Unlock Your Dream Home with a Single Close Construction Loan in NC

Building a home from the ground up in North Carolina is one of the most rewarding financial decisions a family can make. From the rolling foothills of the Piedmont to the coastal plains of the Outer Banks, the state offers some of the most desirable land in the Southeast. But turning a vision into reality requires the right financing strategy from day one and that's exactly where a single close construction loan changes everything.
What Is a One Time Close Construction Loan?
A one time close construction loan, sometimes called a construction to permanent loan, combines two separate financing phases into a single loan product. Instead of applying for a construction loan first and then refinancing into a traditional mortgage once the home is complete, borrowers go through just one application, one approval, and one closing.
This streamlined approach means fewer fees, less paperwork, and far more peace of mind throughout the entire building process.
How the Construction Phase Works
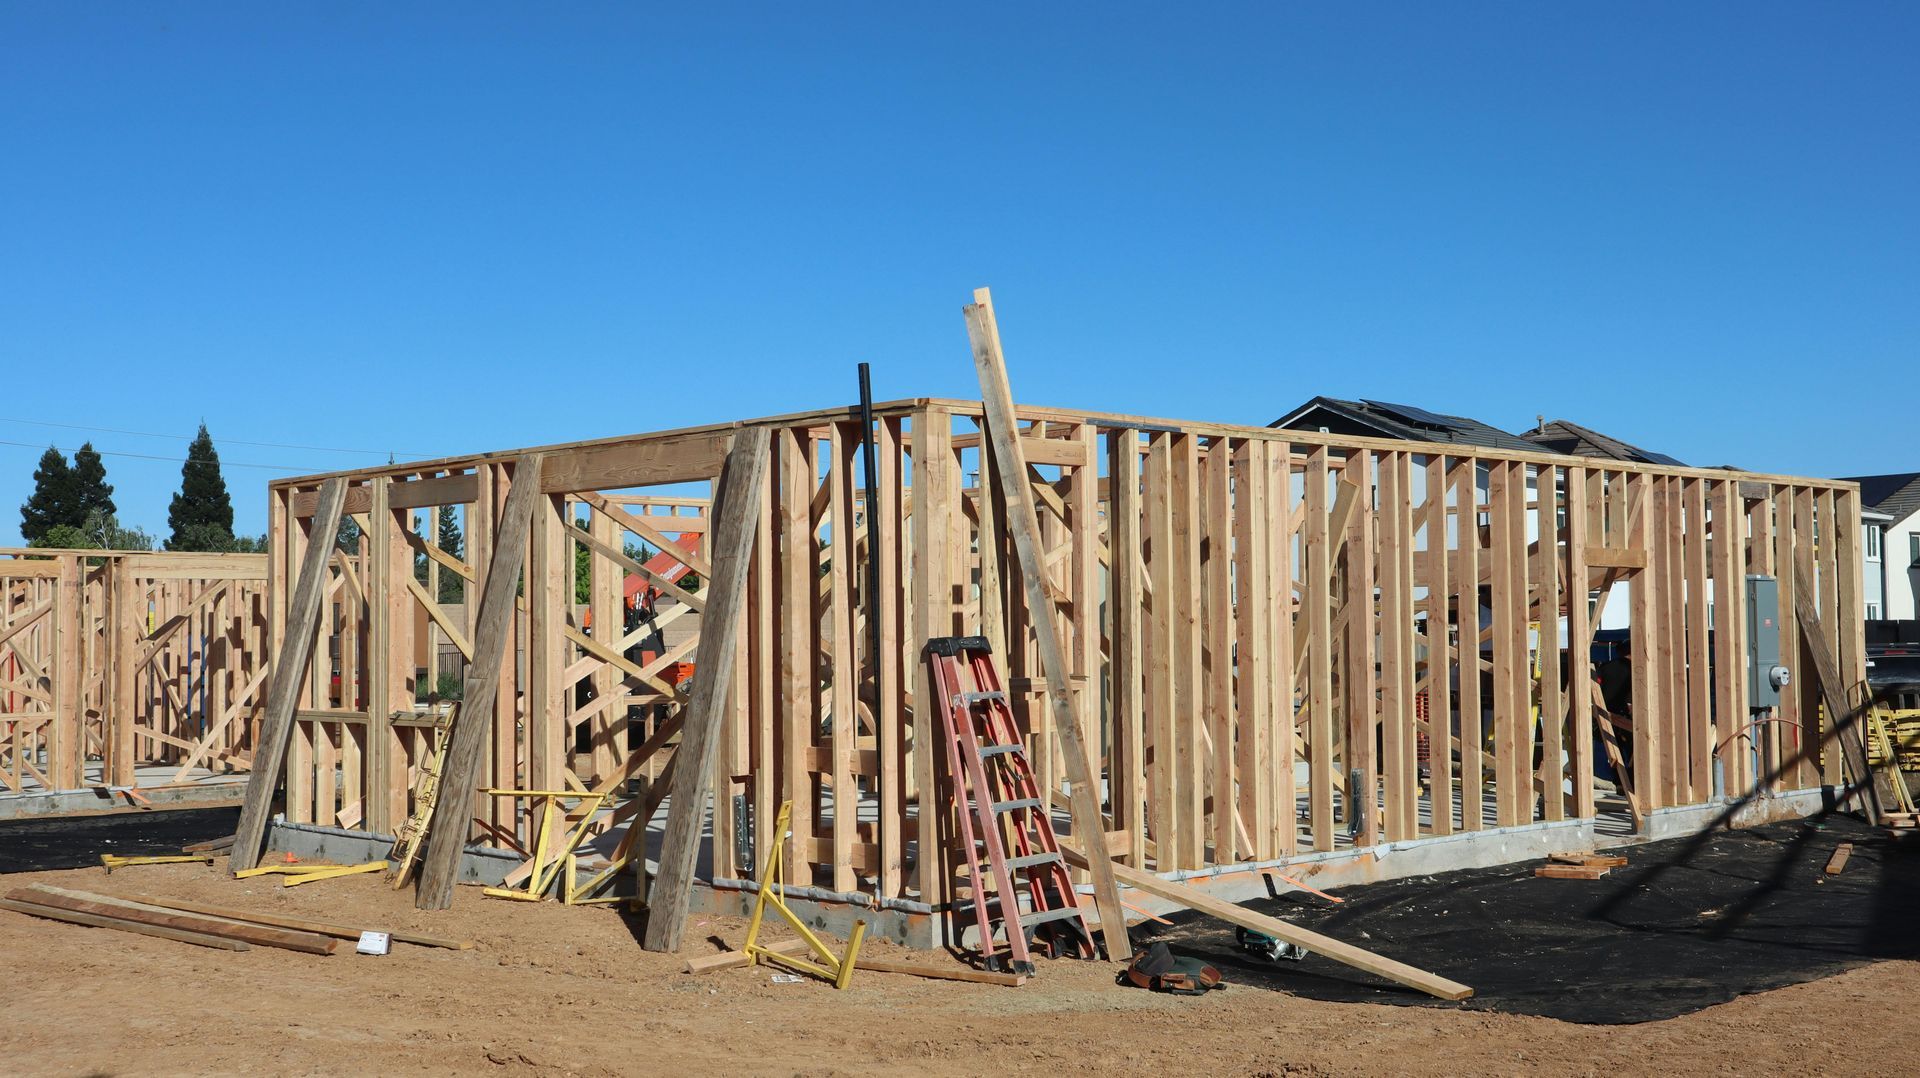
During the construction phase, your funds are distributed in scheduled draws as your builder completes specific milestones foundation poured, framing completed, roofing installed, and so on. During this stage, most borrowers make interest only payments based on the amount that has been drawn, which keeps your monthly costs manageable while your new home takes shape.
Once construction wraps up, the loan automatically converts to a permanent mortgage without requiring a second closing. The interest rates, loan terms, and monthly payments you agreed to at the start remain intact.

Why North Carolina Is an Ideal Place to Build
North Carolina's housing market continues to attract families from across the country. Communities like Wake Forest, Fuquay-Varina, Mooresville, and Waxhaw have seen tremendous growth over the past decade, drawing buyers who want the charm of smaller towns with convenient access to Charlotte and Raleigh. The state's deep historical roots from the Wright Brothers' first flight at Kitty Hawk to the colonial heritage of New Bern give every neighborhood a sense of place that's hard to find elsewhere.
Building in areas like the Lake Norman region, the Triangle, or the growing suburbs of the Triad means your investment is backed by long term economic strength and a steady real estate market.
The Benefits of a Single Loan vs. Two Separate Loans
Choosing this loan type over two separate transactions offers several real advantages:
Closing costs are paid only once rather than twice, which can save thousands of dollars depending on your project size and location. Because your rate is locked at the start, you're protected if interest rates rise during the months your home is under construction. There's also no risk of being denied for the permanent mortgage once construction is complete approval happens at the beginning, giving you and your builder full confidence to move forward.
What to Expect During the Application Process
The application process begins with a review of your credit profile, income, assets, and the details of your construction plans. You'll need to work with a licensed builder and have a signed contract in place, along with a full set of architectural plans and a project budget. These requirements allow the lender to assess the scope and feasibility of the build before funds are committed.
Bob Fabian and his team walk every borrower through each requirement clearly so there are no surprises. Having an experienced guide at this stage makes a genuine difference in how smoothly the entire process unfolds.

Choosing the Right Builder and Lender
Your builder and your lender need to work in close coordination throughout construction financing. Draws must be requested, inspected, and approved on a schedule that keeps your project moving without delays. Choosing a builder who has experience with construction loan programs and a lender who actively manages the draw process is essential.
Bob Fabian has deep familiarity with how to structure these transactions so that the builder, the borrower, and the title company are all aligned from the first day to the final walk-through. That kind of coordination is what separates a smooth build from a stressful one.
Land Purchase and Lot Financing Options
Some construction loan programs allow borrowers to purchase the land as part of the same loan, rolling the lot cost directly into the total financing package. This is particularly useful in North Carolina's competitive land market, where desirable lots in communities near Lake Wylie, Apex, or Holly Springs move quickly. Rather than securing separate land financing and then applying for construction funds, a combined approach simplifies the entire transaction and reduces your total closing costs.
Flexible Terms and Long Term Planning
Modern construction to permanent loan programs offers flexible terms designed to fit a variety of financial situations. Whether you're a first-time buyer building a starter home or a move-up buyer ready for a custom build, the program can be structured around your timeline and budget. Fixed rate options provide certainty over the life of the loan, while adjustable options may offer lower initial payments for buyers who plan to sell or refinance within a specific window.
Bob Fabian takes the time to review all available options with each client so the loan type selected truly serves their long term goals not just the immediate need to get a project started.
Taking the First Step Toward Your Dream Home
Building your dream home in North Carolina starts with a single conversation. Understanding how much you qualify for, what your payments will look like during construction and after it converts, and how to select a builder who meets program requirements are all pieces of a puzzle that come together quickly with the right guidance.
If you're ready to explore construction financing and want a lender who will be with you every step of the way, reach out to Bob Fabian today. The path to a home built exactly the way you want it in the community you've chosen, on the land you've selected begins with getting the financing right from the start.